Could moving to a new bank save you money? Compare a better mortgage rate—or explore a buyout with extra funds released from your property.
No account neededSave and returnPrivate results link
A clearer way to compare
Sample figures only. Your comparison uses your own mortgage details.
ONE PROPERTY. TWO WAYS FORWARD.
What would you like your mortgage to do?
Explore the cost of switching in Dubai, Abu Dhabi and across the UAE, with the extra borrowing shown clearly if you want to release equity.
MORTGAGE BUYOUT
A better rate on the loan you already have.
Move your existing mortgage to another bank and explore whether a different rate can reduce your monthly payments and full-term interest.
Compare the same outstanding balance
See savings over your remaining tenure
Weigh switching fees against any bank refund
BUYOUT + EQUITY
A fresh mortgage. Capital for your next move.
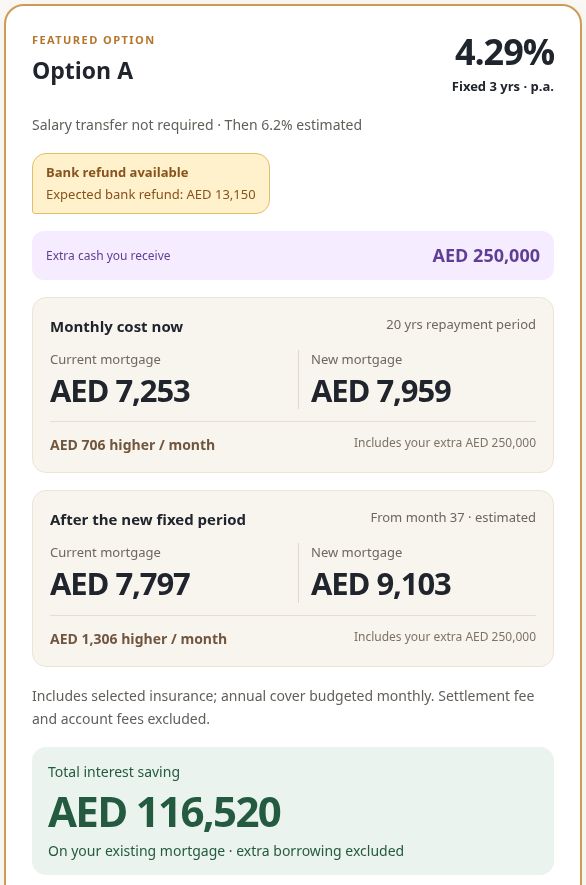
Switch the existing loan and explore additional borrowing against your property. See the requested cash release alongside the payment on the larger loan.
Enter how much extra funding you want
See the new payment including those funds
Keep existing-loan savings separate from extra borrowing
SEE WHAT YOU’LL GET
Your mortgage numbers, side by side.
Monthly payments are only the start. Compare the follow-on period, total interest, insurance, fees and any applicable bank refund before choosing your next step.
BUYOUT EXAMPLE
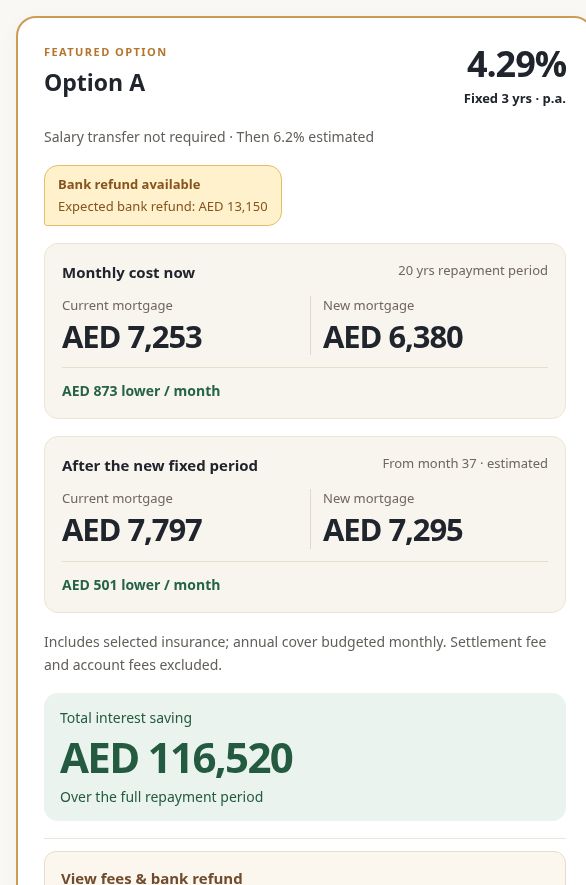
Switch to explore lower costs
The same AED 1 million balance, compared over 20 years. Both the initial payment and the later variable payment are visible.
Illustrations, not live bank offers. These screenshots use fictional inputs. Rates, savings, refunds and borrowing amounts depend on the selected product and your details.See the example assumptions
Outstanding balance AED 1,000,000; property value AED 2,000,000; 20 years remaining and proposed. Current rate 5.69% fixed for 14 more months, then 6.70%. New rate 4.29% fixed for 36 months, then 6.20%. Life cover is 0.02% monthly on the current reducing balance and 0.01% on the new balance; annual property cover is 0.04%. The equity example adds AED 250,000. Sample fees and AED 13,150 refund are illustrative. Variable rates are held constant; savings on the existing loan exclude interest on additional equity. These are not advertised bank terms.
LOOK BEYOND THE FIRST PAYMENT
A lower rate is a starting point. The full picture matters.
The repayment period
Compare the same tenure first. Extending it can lower monthly payments while increasing total interest.
The rate after the fixed period
When selected, compare both mortgages at matching points in time using their own fixed and follow-on periods.
The real cost of the move
See fees, insurance and applicable refunds. A later bank refund is separate from the cash needed upfront.
FROM DETAILS TO DECISION
A simple start. A considered next step.
01
Tell us about your loan
Add the figures you know—your bank, balance, tenure, rate or instalment, and property value. Your progress is saved.
02
Explore comparable options
Complete the required details for available instant comparisons. If information or product terms need checking, our team will prepare your review.
03
Choose what happens next
Save the unique link to your email, check eligibility for a selected option, or ask your assigned consultant to help you proceed.
YOUR QUESTIONS, ANSWERED
Mortgage switching & equity release explained.
Understand the choices before you compare.
What is a mortgage buyout in the UAE?
A mortgage buyout moves your outstanding home loan from your current bank to a new lender. A different rate or repayment structure may reduce your costs. Fulus compares payments, interest, insurance, switching charges and applicable refunds so you can assess the move.
Can I save interest without extending my mortgage tenure?
You can start by comparing both loans over your existing remaining tenure. A lower rate may reduce interest and monthly payments, depending on the fees and follow-on rates. You can also adjust the proposed tenure and see how this changes the result.
How does buyout + equity release work?
The new mortgage pays off your existing loan and includes additional borrowing against your property. The amount you can release depends on the bank’s valuation, permitted financing level, your outstanding balance and eligibility. The tool illustrates the extra amount you request; it does not confirm a borrowing limit.
Will my monthly payment increase if I release equity?
It can. You are borrowing more, even if the new rate is lower. The equity comparison includes the extra funds in the new monthly payment and shows interest savings on the existing mortgage separately, so you can distinguish the cost of switching from the cost of extra borrowing.
Which fees and bank refunds should I compare?
Look at bank processing and valuation charges, mortgage release and registration, the existing bank’s settlement charge, and insurance. Selected products may reimburse settlement or valuation fees. Your review separates upfront expenses, the expected bank refund and the resulting net cost or surplus.
How are fixed and variable rates compared?
When follow-on comparison is selected, each mortgage uses its own remaining fixed period and the entered follow-on rate or margin plus EIBOR for the rest of the term. Variable-rate estimates hold the selected benchmark constant; future EIBOR and actual payments may change.
Can I compare an Islamic home finance facility?
Yes. Select Islamic or conventional for your current loan. Enter your current interest or profit rate and any known follow-on terms. Available new options depend on the live products and information selected for your comparison.
What do I need to start?
Have your outstanding balance, remaining tenure, current rate or monthly instalment, current bank and estimated property value ready. Add your name and a phone number or email. Save what you know; if something needs checking, the Fulus team can help complete the review.
FULUS SWITCH, SAVE & RELEASE EQUITY
Find out what a switch could mean for you.
Bring your mortgage details. We’ll help you see the options clearly.